ONE QUESTION TO ASK YOUR ADVISOR

Your retirement.
Your money.
Are you prepared?

Before a major decline forces the conversation, ask what your retirement plan could actually withstand.

Review Your Preparedness →

Ask while you still have choices.

PUT YOUR PLAN TO THE TEST

If markets fell by

50%or more

and took

3–7years

to recover…

How would you fund your life?

A hypothetical stress test—not a prediction of market losses or recovery time.

Your retirement income

If markets fell by 50% or more and took 3–7 years to recover, are you prepared for that?

Ask your advisor to walk through what that scenario would mean for your portfolio, your income, and your retirement plans. Where would your spending money come from? What would have to change? A market returning to its previous high does not necessarily mean your own account has recovered after years of withdrawals. This is a hypothetical stress test, not a prediction of the size or duration of the next decline.

THE FOLLOW-UP

Show me how my retirement plan would fund my life through that scenario—and where it could fall short.
WHAT A SERIOUS ANSWER SOUNDS LIKE

“Stay the course” could cost you years you cannot get back.

If markets fell by 50% or more and took 3–7 years to recover, your bills would not wait. Neither would your retirement. A plan that depends on enduring the decline must explain how you would fund those years, what you might have to give up, and whether continued withdrawals could leave you behind even after the market recovered. “Markets come back” does not answer any of that.

Remaining invested may be appropriate when that exposure fits your needs and resources. Reducing it can create taxes, missed gains, and difficult reinvestment decisions. Your advisor should explain those trade-offs against the consequences of a major loss in your own retirement plan. A familiar slogan is no substitute for that work.

Before you agree to stay the course, insist on knowing how your retirement would withstand it.

MY CONVICTION · YOUR RETIREMENT

I believe we are on the doorstep of a major financial reset.

I believe the risks are serious enough to threaten the retirement security people spent a lifetime building. That conviction is why I wrote this book.

THE BOOK BEHIND MY WORK

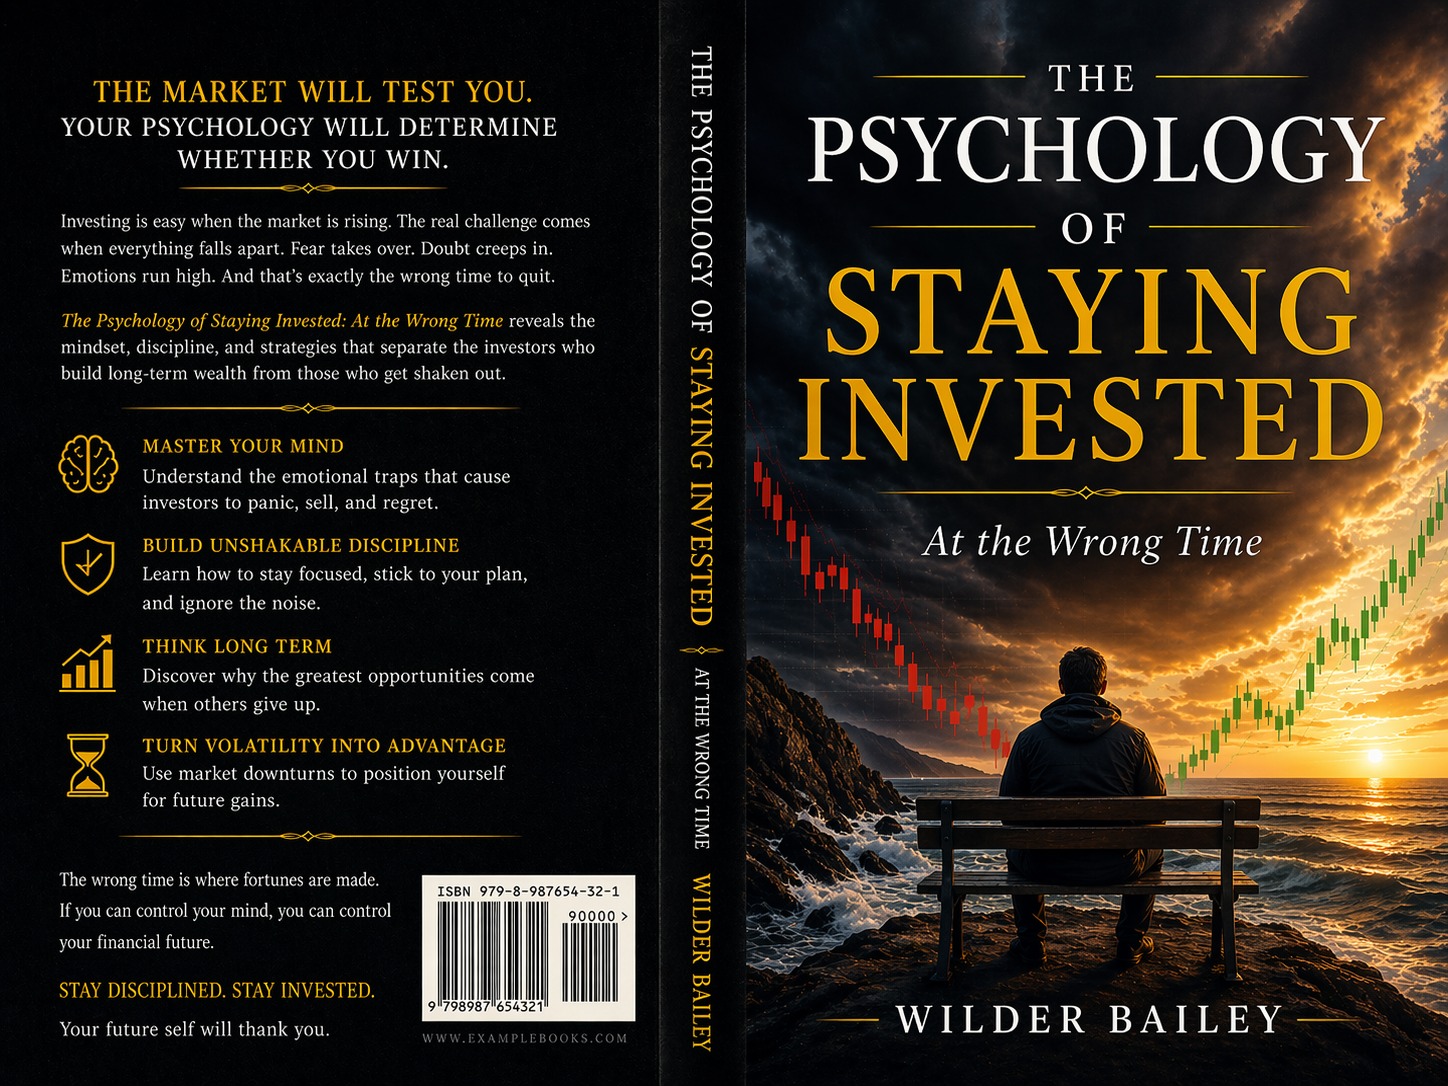
Front cover of The Psychology of Staying Invested at the Wrong Time by Wilder Bailey.

The Psychology of Staying Invested at the Wrong Time

Wilder Bailey

View the book on Amazon ↗

FROM CHAPTER 16

Selling Is a Skill

“The skill of selling is rarer, harder, and more valuable than the skill of buying.”

“The system you build for selling must overcome these forces. Willpower will not. Insight will not. Good intentions will not. What works is structure — specifically, written structure, prepared in advance, that takes the decision out of the moment in which the psychological forces are operating and commits the retiree to a sequence of actions that the current, calm version of himself has pre-authorized.”

Selected passages from Chapter 16 · © 2026 Wilder Bailey

WHY THIS MATTERS TO YOUR RETIREMENT

My work challenges the comfort of staying invested without examining what you own, what you paid, and what you could lose. The book addresses the psychology. The work we do together addresses your choices.

Explore the book and my approach →

WHAT IS AT STAKE

Your spending.
Your plans.
Your years.

Wilder BaileyFounder, Bailey Financial Services, Inc.

For someone drawing income, a major decline can mean reduced spending, postponed plans, and years spent trying to recover while withdrawals continue. My work is focused on examining that exposure, preserving financial flexibility, and preparing to recognize opportunity when investment values improve.

I cannot tell you when markets will turn, and these measures do not establish a timetable. But I believe waiting for the damage to become obvious is a dangerous way to make retirement decisions.

You deserve to know what your advisor plans to do before your retirement is put to the test.

Ask this question now.

TAKE THE NEXT STEP

Are you prepared for that?

If you are unsure, start with a Portfolio Preparedness Review. Identify the areas of your investment and retirement strategy that deserve a closer look—and bring this scenario into the conversation.

Start Your Portfolio Preparedness Review

Prefer to talk? Start a conversation with Wilder.

Watkinsville, Georgia · Wilder@BaileyFS.net

CONTINUE READING

Bailey Financial Services, Inc. is a fee-only, state-registered investment adviser. This page reflects the author’s analysis and opinion and is provided for general informational purposes only. It is not individualized investment advice or a recommendation to buy or sell any security. Market outcomes and the timing of any decline are uncertain. All investing involves risk, including loss of principal. Diversification and risk-management strategies cannot guarantee profits or prevent losses. Decisions should reflect your individual circumstances, objectives, taxes, and liquidity needs. Bailey Financial Services is not affiliated with Warren Buffett, Robert Shiller, or Ray Dalio and receives no compensation for referencing their work. References do not imply endorsement in either direction or agreement with the author’s market outlook.