Wilder Bailey · Why my work is different

I believe we are standing at the edge of a market reset that could reshape retirement plans for years.

THE RECOVERY MOUNTAINDown 40%.
Up 66.7% to get back.
A forty percent loss requires a sixty-six point seven percent recoveryAn illustrative account falls from one hundred thousand dollars to sixty thousand dollars, then climbs back to one hundred thousand. The percentage gain is larger because it starts from a smaller amount. Horizontal distance does not represent time.$100,000$100,000$60,000−40%+66.7%

Getting back takes more.

After a loss, the gain is calculated on a smaller balance. A 40% gain would bring $60,000 to just $84,000.

Illustrative arithmetic: $40,000 ÷ $60,000 = 66.7% (rounded). Excludes withdrawals, fees and taxes. No recovery timing or investment performance is predicted.

Protect what your capital makes possible. Consider precious metals where they serve a purpose. Prepare to buy productive investments at better prices.

What you carry into the reset matters

A reset can take away years.
Preparation can preserve choices.

Imagine investments you wanted to own becoming available at half the price. Would you have the capital—and the confidence—to buy? Or would you be waiting for your own portfolio to recover?

That is why I look beyond the decline itself. A substantial loss can consume years of recovery. Capital preserved through that same decline may give you the ability to purchase more ownership at a lower price. Both consequences deserve a place in the plan.

01 · The recovery burden

How much ground must you regain?

A deep loss changes the starting point for everything that follows.

Starting value100%
After a 50% decline50%
+100%Gain needed just to return
to the starting value.

Meanwhile, retirement spending continues. Withdrawals during the decline can make the climb back harder.

02 · The buying opportunity

How much more could your capital buy?

Consider the purchasing power of the same $100,000 available to invest.

At $100 per unit1,000 units
At $50 per unit2,000 units
2×The ownership purchased
with the same available dollars.

You would own more units from that purchase. What they ultimately earn or become worth remains uncertain.

Illustrative arithmetic—not strategy performance or a forecast. Left: a 50% loss requires a 100% gain to recover, excluding withdrawals. Right: $100,000 divided by a hypothetical unit price of $100 or $50. Each block represents 250 units. Assumes the full $100,000 is available at either purchase price; it does not assume an investor can avoid a decline, preserve that amount, or identify a market bottom. Both illustrations exclude fees, taxes, income, and inflation.

Where my work comes in

Preserve the ability to act.

I want to examine what can be protected before a reset, what could remain resilient through it, and what would make a lower-priced investment worth buying. Precious metals may have a role: if they hold up better than equities, a portion could later be exchanged for more equity ownership. That relationship is possible, not assured.

The opportunity begins with having capital available—and a plan for using it when value improves.

Buffett · Shiller · The price of staying invested

Two valuation lenses.
One concern I cannot ignore.

What are investors paying for the economy—and what are they paying for the earnings it produces? The Buffett Indicator and Shiller CAPE put those questions at the center of my work.

My concern about a major reset begins here. I believe investors are paying prices that leave too little room for disappointment. A great company, a powerful technology, or a growing economy does not make every purchase price reasonable.

Before asking how much further a market can rise, I want to examine how much of its future success is already in the price.

THE ECONOMY LENS

The Buffett Indicator

LATEST SOURCED READING
234.7%
September 11, 2026 · GuruFocus
Latest reading Reference average: 130.53%

The U.S. stock market is valued at about 2.35 times annual GDP. This reading is roughly 1.80 times the provider’s recent 20-year average.

Reference: 130.53%, GuruFocus’s recent 20-year average. This is the standard market-cap-to-GDP measure, without a Federal Reserve balance-sheet adjustment.

GuruFocus · View source →

Total stock-market value ÷ annual U.S. economic output.

This comparison puts the price of the U.S. stock market alongside the scale of the economy beneath it. It asks how much investors are paying for ownership relative to the economic activity supporting those businesses.

I use it to challenge the idea that rising prices, by themselves, confirm a sound investment. A market can keep advancing while the price paid becomes harder to justify.

My Buffett Indicator page examines the valuation gap, historical context, and what that means for someone depending on a portfolio for retirement.

EXPLORE THE EVIDENCEBuffett Indicator
THE EARNINGS LENS

The Shiller CAPE

LATEST SOURCED READING
40.73×
September 10, 2026 · 4:00 p.m. EDT · Multpl
Latest reading Reference average: 17.42×

Investors are paying about $40.73 for each $1 of ten-year average inflation-adjusted earnings. That is roughly 2.34 times the series’ historical mean.

Reference: historical mean 17.42×. Multpl reports a historical monthly maximum of 44.19× in December 1999. This current estimate is not Shiller’s monthly data release.

Multpl · View source →

S&P 500 price ÷ ten-year average inflation-adjusted earnings.

This comparison looks through the fluctuations of a single earnings year. It asks how much investors are paying for earning power measured across a longer period.

I use it to question whether a retirement plan is assuming too much from investments bought at demanding prices. Strong businesses still need time to earn what their valuations already anticipate.

My Shiller page puts the measure alongside earlier valuation extremes and examines why the starting price deserves attention before committing capital.

EXPLORE THE EVIDENCEShiller CAPE

Dated snapshots, checked September 11, 2026; not live feeds. The gauges use different units, scales, and historical reference periods. Averages are context, not fair-value targets. Animation illustrates the readings; it does not measure crash probability, expected losses, or when prices will turn.

How these valuations shape my decisions.

I want these valuation questions to affect the decisions we make. How much equity exposure is justified? What loss could the retirement plan absorb? What capital should remain available? What would make an investment attractive enough to buy more?

The same discipline applies on the other side of a reset. When prices become more reasonable relative to the economy and earnings, I want to reassess the opportunity with the same seriousness that led me to question the risk.

Neither indicator supplies a crash date, a guaranteed loss, or a precise buying signal. They measure related aspects of valuation, not independent proof of an inevitable outcome. Economic structure, overseas earnings, accounting changes, and the historical baseline affect interpretation. Expensive markets can continue rising.

Read both analyses. They explain why I believe preparation deserves attention now—and why lower prices could eventually give us a very different reason to act.

Why the size of a loss matters

Recovery begins from what remains.

A percentage loss and an equal percentage gain do not cancel each other. The deeper the decline, the larger the subsequent gain needed just to restore the starting value.

−20%
+25%
Loss → gain required to recover
−40%
+66.7%
Loss → gain required to recover
−50%
+100%
Loss → gain required to recover

Mathematical relationships, not forecasts. Required recovery = loss ÷ (1 − loss). Rounded where shown. No withdrawals, contributions, fees, taxes, or inflation are included.

For a retiree taking distributions, the challenge can be greater. Selling investments to meet expenses during a decline leaves fewer shares participating in a later recovery. Returning to an old index high does not necessarily restore the household’s account—or its purchasing power.

Why I wrote the book

The hardest decision can be changing a familiar course.

In The Psychology of Staying Invested at the Wrong Time, I explore why intelligent, disciplined people can recognize risk and still find it difficult to respond.

The book examines the pull of an old account high, the comfort of a familiar investment story, the reassurance of the crowd, and the reluctance to reconsider a position held for years. It also examines changing market leadership, inflation, interest rates, and the particular demands of retirement withdrawals.

One question runs through that work: If you inherited your portfolio in cash today, would you choose to rebuild what you already own?

Your answer may reveal a gap between a portfolio accumulated over time and one you would deliberately choose now. Taxes, income needs, and other constraints matter when deciding how to address that gap.

The book explains the framework. This page explains how I bring it to my work—and the conviction that makes that work especially urgent to me.

View the book on Amazon
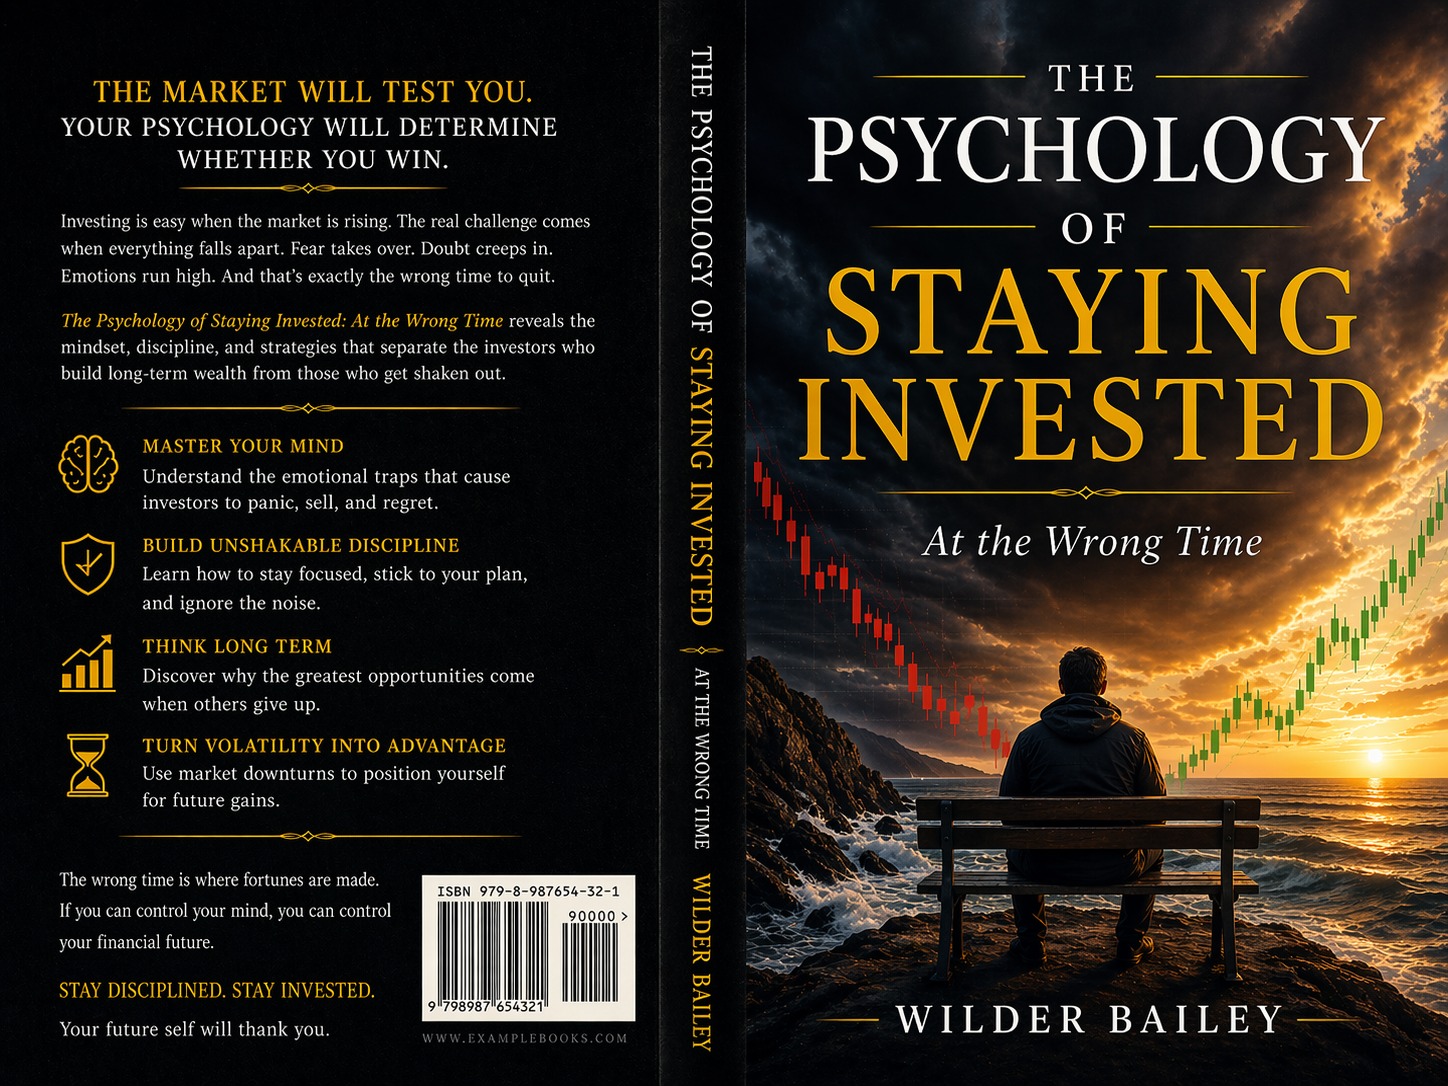
Front cover of The Psychology of Staying Invested at the Wrong Time by Wilder Bailey, showing a man looking across the sea beneath falling and rising market charts.

Read an Excerpt: Selling Is a Skill

What patience is for

Wait for value. Prepare to recognize it.

John Templeton looked for investments where pessimism had driven prices down. Warren Buffett has emphasized value, financial strength, and the discipline to resist the crowd. Those ideas require independent judgment before a decision feels comfortable.

Templeton’s search for bargains and Buffett’s willingness to wait for attractive opportunities inform how I think about price. Their approaches are not identical to mine. Buffett also advocates low-cost index investing for many investors and has been explicitly critical of gold. My case for precious metals is my own.

Read the Templeton Foundation biography and Buffett’s 2004 and 2011 shareholder letters.

01 · BEFORE A RESET

Examine the exposure.

Assess valuations, concentration, withdrawal needs, and the amount of loss a household can absorb. Decide what capital needs to remain readily available.

02 · THROUGH A RESET

Keep choices available.

Manage liquidity and risk. Consider assets that respond differently to economic stress, including an appropriately sized precious-metals allocation.

03 · AS VALUE IMPROVES

Put capital to work.

Reassess business quality, prices, and risk. Use a written process for buying in stages while maintaining the resources needed for retirement income.

Where precious metals fit

A potential source of resilience—and future buying power.

I take gold seriously because financial stress can involve confidence in money as well as confidence in companies. An asset with different sources of demand can serve a useful role when familiar portfolio relationships change.

The World Gold Council’s research documents gold’s diversification potential during periods of market stress. It also acknowledges volatility, periods of underperformance, and the absence of regular income. The Council is a gold-industry organization; its research should be read with that perspective in mind.

Read the diversification research →

The relative value matters.

If gold holds its value or rises while equities fall, selling a portion of that gold could finance more equity ownership than it could before. That potential change in buying power is part of the reason I consider metals within a broader plan.

It is conditional. Gold can fall too, including during a rush for liquidity. Silver and mining shares have different risks and should not be treated as interchangeable with gold bullion. Metals do not replace a plan for meeting expenses.

Position size, the investment vehicle, custody, costs, taxes, and the reason for holding it all matter. I would also want a reason for reducing the position when other opportunities become more attractive.

The objective is to keep evaluating where capital can do the most useful work.

Gold’s risks and challenges

The work on the other side

Being defensive creates a responsibility to be ready.

A plan that reduces risk but never explains how to increase investment exposure again is unfinished. Fear can keep someone out of a reasonably priced market just as confidence can keep someone in an expensive one.

I want the buying process discussed before a difficult market arrives: what makes an investment attractive, how purchases could be staged, how much liquidity must remain, and what evidence would change the decision.

Lower prices alone do not make an investment a bargain. Earnings, debt, business durability, and the price paid relative to those fundamentals still matter. Nor can anyone count on recognizing the bottom.

My willingness to become more constructive when value improves is essential to the approach. Caution needs a purpose, and that purpose includes being prepared to own more when the opportunity justifies it.

Where I stand

I believe the risk deserves action before the damage.

I believe we are facing the possibility of a massive market reset—one that could be among the most consequential of our lifetimes. I believe it could begin soon, and that regaining today’s market values afterward could take years.

That is my conviction and risk assessment, not a reliable forecast of when markets will turn or how far they will fall. I can be early. I can be wrong. The depth and duration of any recovery are unknowable in advance.

But I do not believe uncertainty excuses leaving the exposure unexamined. My responsibility is to bring my judgment to the work, explain it clearly, and build a plan that can adapt as the evidence changes.

I would rather have a difficult conversation about preparation today than discover, after a major loss, that we never had a plan for it.

— Wilder Bailey
A conversation about your future

Let’s look at what your capital needs to do next.

You do not have to share every part of my outlook to benefit from a careful conversation about risk, income, and opportunity.

My story is larger than I can put on a page. A brief visit gives us the opportunity to discuss your circumstances, examine how I think, and decide whether working together could be a good fit.

Start with your questions.

Bring your concerns about today’s market and the retirement you want your money to support. Ask me about the book and the approach behind it.

Start a conversation

Wilder Bailey · Watkinsville, Georgia
Wilder@BaileyFS.net

Continue the conversation

Explore the thinking behind the approach.

Sources and further reading

Prepared September 11, 2026. Sources accessed on that date.

  1. Wilder Bailey, The Psychology of Staying Invested at the Wrong Time: How Cycles Are Made, Missed, and Survived (2026). Introduction; Chapters 4–9, 13–18; conclusion. Page adapted from the author’s supplied manuscript, with his present outlook expressed separately.
  2. John Templeton Foundation, biography of Sir John Templeton (undated). His contrarian search for value.
  3. Warren Buffett, 2004 shareholder letter (2005), printed pages 3–4. Patience, available cash, investor behavior, and indexing.
  4. Warren Buffett, 2011 shareholder letter (2012), printed pages 17–19. Liquidity, productive assets, and his criticism of gold.
  5. World Gold Council, gold’s diversification attributes and potential risks and challenges (February 4, 2026). Industry-sponsored research.
  6. Warren Buffett, Fortune, December 10, 2001, original article preserved by Berkshire Hathaway, PDF page 6. Historical market-value-to-GNP warning.
  7. Robert J. Shiller, Irrational Exuberance, third edition (2015), Chapter 1, publisher’s excerpt, pages 2 and 6. Valuation, earnings, and inflation-adjusted price recovery.
  8. Related analysis by Wilder Bailey: The Buffett Indicator and The Shiller CAPE. These pages explain each valuation measure and provide their underlying sources and dated readings.
  9. Buying-power and loss-recovery illustrations: basic arithmetic, independently calculated. They show no actual or projected investment strategy performance.

Bailey Financial Services, Inc. is a fee-only, state-registered investment adviser. This page reflects Wilder Bailey’s analysis and opinion and is provided for general informational and educational purposes. It is not individualized investment advice or a recommendation to buy or sell a security or precious metal. All investments involve risk, including loss of principal. Neither diversification nor a defensive allocation guarantees protection or superior performance. Past performance does not guarantee future results. Decisions depend on individual circumstances, objectives, taxes, costs, and liquidity needs.

References to John Templeton, Warren Buffett, Robert Shiller, Berkshire Hathaway, the John Templeton Foundation, and the World Gold Council are for educational context. Bailey Financial Services is not affiliated with these parties; no compensation is paid or received for these references, and the references do not imply endorsement in either direction. Their approaches and circumstances differ from those of a household drawing retirement income.

CHAPTER 16 · BOOK EXCERPT

Selling Is a Skill

From The Psychology of Staying Invested at the Wrong Time
By Wilder Bailey · Approximately 5 minutes

I want to begin this chapter by telling you something that, after thirty years in this business, I have come to believe with unusual conviction.

The skill of selling is rarer, harder, and more valuable than the skill of buying.

I do not mean this as a provocation. I mean it precisely. Buying well is difficult, but the world has an enormous industry — analysts, brokers, financial television, newsletters, podcasts, friends, brothers-in-law — whose entire function is to generate buying ideas. Any retiree who wants buying ideas will find them. The supply is effectively unlimited. Whether the ideas are any good is a separate question, but the ideas themselves are everywhere.

Selling is different. The world has, by comparison, almost no infrastructure for generating selling ideas. Financial television does not run segments on what to sell; it runs segments on what to buy. Advisors generally do not build their practices around the conversation that ends with a client’s position reduced; they build them around the conversation that ends with a client’s position added to. The literature on investment behavior is thick with books on how to pick stocks and thin with books on how to let them go. The investor who wants to learn how to sell well is largely on his own.

This is not an accident. Buying is comfortable because buying is aligned with hope — the hope that the new position will go up, the hope that the thesis will be vindicated, the hope that the investor’s judgment will be confirmed by the market. Selling is uncomfortable because selling is aligned with reckoning — the reckoning of a purchase decision that may not have worked, the reckoning of a story that may no longer be true, the reckoning of a position the investor has grown attached to but may not actually need. Hope is easier than reckoning, and an entire industry has arranged itself around the easier emotion.

The retiree, for whom the rotation out of the accumulation-phase portfolio into the distribution-phase portfolio is the single most important financial act of his lifetime, cannot afford to be served by an industry that has no practiced vocabulary for what he actually needs to do. He needs to learn the skill of selling. He needs to understand why it is hard. He needs a framework for doing it that works against the psychology we have spent twelve chapters diagnosing. This chapter is meant to supply that framework.

Why Selling Is Hard

Let me enumerate the specific ways in which selling a position is psychologically more difficult than holding it, because naming the obstacles is the first step in disarming them.

Selling is an action; holding is a non-action. The human brain is biased toward inaction in ambiguous situations. This is the well-documented default effect — the tendency, observed across every domain of human behavior, for people to stick with whatever option has been designated as the default when facing uncertainty. In investing, the default is almost always to keep holding what you already own. Selling requires overcoming the default. Holding does not.

Selling produces a definite outcome; holding produces an indefinite one. The sale crystallizes the position. Whatever has happened to the holding is now final; whatever happens next to the market does not change the result of the sale. This is psychologically difficult because it converts a state of ambiguity (where the holder can still tell himself a story about eventual recovery or vindication) into a state of finality (where the story is either confirmed or refuted by the price at the moment of sale). Most people prefer ambiguity to finality. Selling removes the ambiguity.

Selling triggers loss aversion. Kahneman and Tversky’s work on loss aversion established that losses are felt roughly twice as powerfully as equivalent gains. A position that is down thirty percent represents a specific quantity of loss that has not been realized. The loss is, in a financial sense, already there — the position is worth what it is worth, regardless of whether the holder sells. But the holder does not experience the loss until the sale. The paper loss is, in a peculiar psychological sense, not yet real to him. The sale makes it real. Loss aversion therefore pushes strongly against the sale of losing positions, even when the rational case for the sale is clear.

Selling reveals prior judgment. The sale of a position is, at some level, an admission that the position is no longer appropriate to hold, which is uncomfortably close to admitting that some part of the decision to buy or retain the position was mistaken. This produces specific psychological resistance in accomplished people, whose self-image depends on their judgment’s track record. The Hero trap — the overconfidence trap from Chapter 9 — is particularly active in selling decisions, because selling is where the pretense that every holding was a deliberate choice collides with the reality that most holdings accumulated for reasons that no longer apply.

Selling is socially visible in concentrated positions. As I noted in Chapter 6, the long-tenured employee who sells his employer stock is, in a small but real way, making a public statement in the context of his workplace community. The pressure to continue holding is not only internal. It is the pressure of the peer group, and it does not go away because the retiree has read a book.

Default effect. Finality aversion. Loss aversion. Vindication effect. Social visibility. Five psychological forces, each well-documented, each pushing in the same direction: hold, do not sell, delay the decision, wait for a better moment that the market is under no obligation to provide.

The system you build for selling must overcome these forces. Willpower will not. Insight will not. Good intentions will not. What works is structure — specifically, written structure, prepared in advance, that takes the decision out of the moment in which the psychological forces are operating and commits the retiree to a sequence of actions that the current, calm version of himself has pre-authorized.

End of excerpt · Chapter 16 continues in the book.
Copyright © 2026 Wilder Bailey. All rights reserved.

Continue reading on Amazon ↗